After the Expat Wave: How Shifting American Tenant Demographics Are Reshaping Thailand's Rental Market—and Where the Opportunity Now Lives
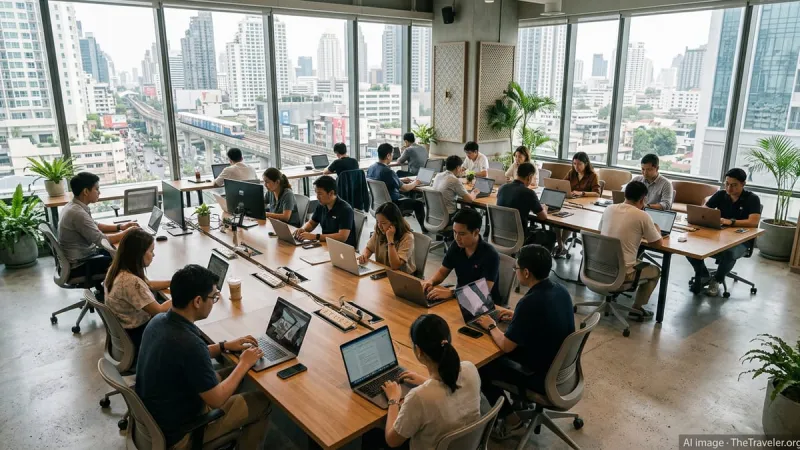
Photo: American expat remote worker working laptop Thailand Bangkok apartment rental, via thetraveler.s3.amazonaws.com
Between 2021 and 2023, Thailand became one of the world's most popular destinations for American remote workers seeking a combination of low living costs, reliable infrastructure, and a high quality of life at a fraction of what comparable conditions would cost in cities like Austin, Denver, or Miami. The influx was real, it was measurable, and it had a tangible effect on rental demand—particularly in Bangkok's central districts and in lifestyle destinations like Chiang Mai and Phuket.
That influx has since moderated. Visa uncertainty, rising living costs, a strengthening baht, and the gradual normalization of remote work policies—with many American employers reintroducing in-person requirements—have contributed to a partial reversal of the trend. The Americans who relocated to Thailand during the peak remote-work era have not all departed, but a meaningful portion have, and they have left behind a rental supply overhang in the neighborhoods they favored.
For American investors holding rental properties in those neighborhoods, the short-term picture is challenging. For those who have not yet entered those markets, the picture is more interesting.
The Geography of the Overhang
The departure effect is not evenly distributed across Thailand's rental market. It is concentrated in specific neighborhoods that disproportionately attracted the American and Western expat remote-work demographic during the 2021–2023 period.
In Bangkok, the most visible impact has been felt in the Ekkamai, Thong Lo, and Ari neighborhoods—areas that combined walkable urban character, established Western dining and café culture, and mid-to-upper-tier residential stock. These neighborhoods saw significant rental price appreciation during the peak demand period, with one-bedroom asking rents in quality buildings climbing 15 to 25 percent above their pre-pandemic baselines.
As American tenants have departed and the supply of available units has increased—partly through new completions and partly through the re-entry of previously owner-occupied units into the rental pool—those elevated rents have begun to correct. In some buildings, effective rents have retraced to near pre-pandemic levels, even as asking rents in listings have been slower to adjust. The gap between asking and achieved rents is a reliable indicator of demand softness and one that investors should verify carefully before underwriting any acquisition in these corridors.
In Chiang Mai, the dynamic is more pronounced. The city attracted a particularly high concentration of American digital nomads and remote workers during the pandemic period, partly because its lower cost profile relative to Bangkok made the math especially compelling for workers whose income was denominated in US dollars. The departure of a portion of that cohort has left a furnished rental supply that materially exceeds current demand in the Nimman and Old City adjacent neighborhoods.
The LTR Visa Variable
Thailand's Long-Term Resident visa program, introduced in 2022, was designed in part to attract exactly the demographic that the remote-work wave had temporarily delivered: high-income foreign nationals with the financial stability and professional credentials to support sustained residency. The program offers a ten-year renewable visa, income tax incentives, and streamlined administrative processes for qualifying applicants.
The LTR visa has generated meaningful interest among American retirees and wealthy professionals, and there is a reasonable case that it will produce a more durable and financially stable inbound demographic than the informal remote-work wave it is designed to complement. LTR visa holders are, by definition, financially qualified and incentivized to remain in Thailand for extended periods—characteristics that translate to lower tenant turnover, more reliable rent payment, and stronger demand for higher-quality residential product.
However, the program's uptake has been slower than initial projections suggested. The administrative complexity of the application process, combined with the income and asset thresholds required for qualification, has limited the program's near-term impact on rental demand. The LTR visa is a structural positive for Thailand's long-term rental market, but it is not a near-term demand replacement for the informal remote-work cohort that has partially retreated.
Investors who purchased or underwrote acquisitions on the assumption that LTR visa demand would arrive quickly and fill the void left by departing remote workers have encountered a timing mismatch. The demand is coming—but the timeline is measured in years rather than quarters.
What the Demand Data Actually Shows
Vacancy rates in expat-oriented rental buildings across Bangkok's central districts have increased meaningfully from their 2022 peaks. Buildings that were running at 85 to 95 percent occupancy during the height of remote-work demand are now, in many cases, operating at 65 to 75 percent occupancy. At that level, rental income is sufficient to cover operating costs in most well-managed buildings, but it does not support the yield projections that were common in underwriting models built during the peak demand period.
The demographic composition of the remaining tenant pool is also shifting. The American remote-work cohort is being partially replaced by tenants from other origin markets—Japanese and Korean expatriates in corporate roles, Southeast Asian professionals, and a slowly growing number of LTR visa holders. These tenant groups have different unit preferences, different lease term expectations, and different willingness-to-pay profiles than the American digital nomad cohort. Buildings and units that were optimized for one demographic may require repositioning to capture the other effectively.
The Contrarian Positioning Case
For investors who are not currently exposed to the affected neighborhoods, the current environment presents a case study in contrarian timing.
The properties most affected by the expat departure effect—furnished, mid-to-upper-tier units in Ekkamai, Thong Lo, Ari, and Nimman—are experiencing price softness that reflects a temporary demand disruption rather than a permanent structural impairment. These are locations with strong underlying fundamentals: established infrastructure, good transit access, proven appeal to high-quality tenants, and a track record of rental demand that predates the remote-work wave by many years.
The investment thesis for acquiring in these neighborhoods now rests on two premises. First, that the LTR visa program will, over an 18-to-36-month horizon, generate a replacement demand cohort that is financially stronger and more stable than the informal remote-work cohort it succeeds. Second, that the current softness in asking prices and achievable rents represents an entry point that will be unavailable once that replacement demand materializes.
Neither premise is guaranteed. The LTR program could underperform. The departure of American remote workers could prove more permanent than cyclical analysis suggests. These are real risks, and they should be reflected in conservative underwriting assumptions—lower initial occupancy projections, wider yield spreads, and longer hold periods than a peak-demand acquisition would require.
Practical Implications for American Investors
Investors currently holding rental properties in the affected neighborhoods should resist the temptation to respond to softening rents by making premature capital expenditures or repositioning decisions. The fundamentals that made these locations attractive have not changed; the demand disruption is real but likely temporary. Maintaining competitive pricing and focusing on tenant quality over short-term yield maximization is the appropriate posture for the current phase of the cycle.
For investors evaluating new acquisitions, the current environment warrants serious attention. Entry prices in some of these neighborhoods are at levels that have not been accessible since the pre-pandemic period, and the supply of motivated sellers—including departing expats liquidating properties they purchased during the demand surge—is higher than it has been in several years.
The 18-to-36-month window referenced above is not a guarantee. It is an analytically grounded estimate of the time required for LTR visa demand to scale, for the supply overhang to absorb, and for the rental market in these neighborhoods to return to equilibrium. Investors who enter before that equilibrium is restored will do so at lower prices and with the patience required to see the thesis through.